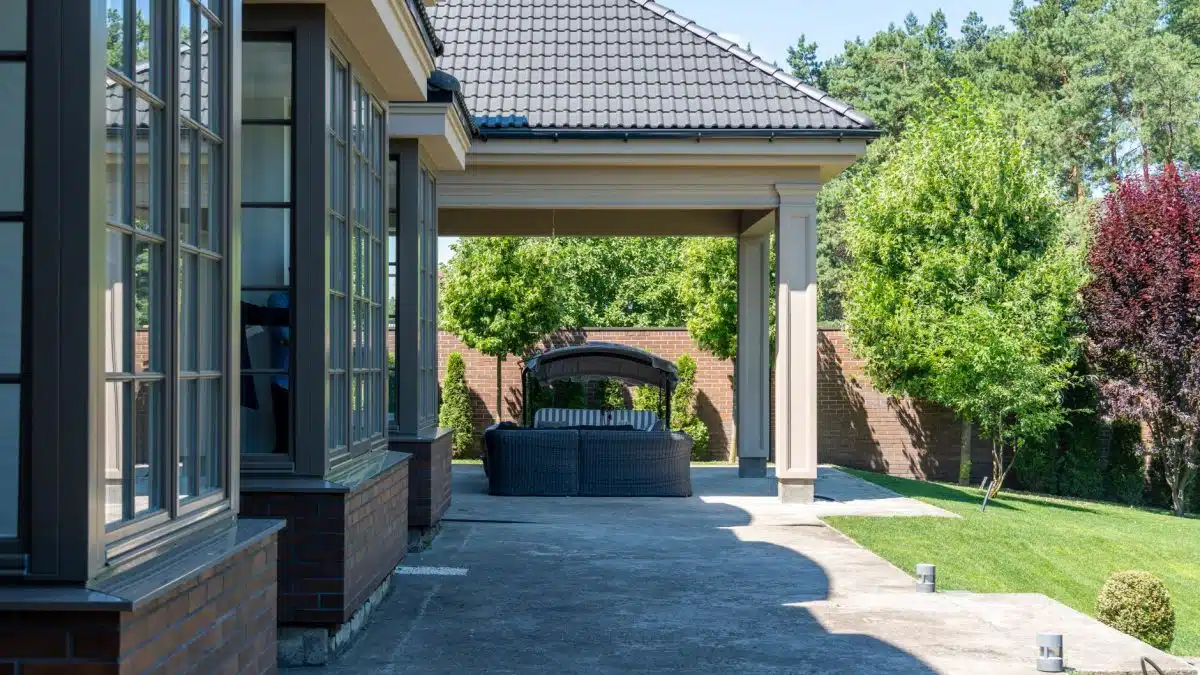
If your home carries a FORTIFIED Roof designation, perhaps one earned through the Louisiana Fortify Homes Program, adding a patio cover raises a fair question anywhere from Kenner to Mandeville: will attaching it affect the designation, or the insurance discount that came with it? The answer depends on how the patio cover meets the house and the FORTIFIED roof, and the answers come from FORTIFIED, working from your evaluator’s documentation, and from your insurance company, not from an installer.
It’s general information, not insurance or legal advice, so talk with a FORTIFIED evaluator and your insurance agent about your specific home before you build.
Key takeaways
- A FORTIFIED technical bulletin lists patio covers connected to the home as accessory structures, and an accessory roof that ties into the main roof cover must also meet FORTIFIED Roof requirements.
- The same bulletin treats an accessory roof as completely separate only when adequate vertical separation keeps it from touching or interfering with FORTIFIED components on the main roof, such as edge details.
- The 2025 FORTIFIED Home Standard says items that penetrate the FORTIFIED roof or roof cover require additional design and installation documentation.
- FORTIFIED advises talking with a FORTIFIED evaluator before making exterior modifications to a designated home.
- Louisiana law requires insurers to provide actuarially justified discounts or credits for homes built or retrofitted to FORTIFIED standards, and the statute’s text doesn’t name a percentage.
What the Louisiana Fortify Homes Program and FORTIFIED Roof cover
The Louisiana Department of Insurance (LDI) runs the Louisiana Fortify Homes Program, which grants up to $10,000 for homeowners to upgrade their roofs to standards set by the Insurance Institute for Business & Home Safety (IBHS). Its eligibility rules say only primary residences can participate, and the home must be covered by an active residential insurance policy with wind coverage. As of September 15, 2026, the program page says lottery registration is closed and additional grant rounds will be announced at a later date.
A designation doesn’t last forever. LDI says FORTIFIED Roof certificates are good for 5 years, and homeowners need to retain an evaluator to reinspect the home to renew. FORTIFIED’s own FAQ adds that when a home has been modified since designation, for example by enclosing an attached porch, the evaluator works with the owner to determine whether the home still meets the standards.
Does a patio cover affect a FORTIFIED roof in Louisiana?
It can. The answer turns on how the cover’s roof relates to the main roof. FORTIFIED Technical Bulletin FH 2023-03 says accessory structures “include, but are not limited to sunrooms, patio covers, porches, carports, and pergolas that are connected to the home.”
The bulletin then draws the line. An accessory roof not over livable space that ties into the main roof cover is also required to meet FORTIFIED Roof new roof requirements, while “accessory roofs that are completely separate from the main roof are not required to comply with FORTIFIED requirements for the Roof level of designation.” The 2025 FORTIFIED Home Standard’s scope list lines up with that. It puts “any roof type that ties into the main roof cover” inside the FORTIFIED scope and lists exterior roofs “not over living space of the home or tied into the main roof cover” as outside it.
Attachment details matter as well. The 2025 standard says “any items that change the home structurally, penetrate the FORTIFIED roof or roof cover, interfere with FORTIFIED edge details or otherwise put the home at an increased risk of damage during high winds require additional design and installation documentation and must follow FORTIFIED guidance when available.” It also limits where roof-mounted equipment or structures may touch the roof cover to properly flashed and sealed structural penetrations.
Attachment approaches to discuss with your evaluator
- Completely separate. The bulletin says an accessory roof may be considered completely separate when adequate vertical separation means no material overlaps or touches, and the accessory roof, including its flashing, won’t interfere with FORTIFIED Roof components on the main roof, such as edge details. A cover on its own posts doesn’t pass that test automatically if it sits tight against the roofline.
- Tied into the main roof. If an accessory roof is connected to or integrated with the main roof cover, the bulletin says both roofs must meet FORTIFIED Roof New Roof requirements, with documentation for each.
- Meeting the main roof at the eave or edge. The bulletin calls this condition a red flag that needs more information along the intersection of the two roofs. If the accessory roof prevents installation or documentation of FORTIFIED edge details on the main roof, the bulletin says the home is only eligible for the FORTIFIED Roof Existing Roof designation, not New Roof.
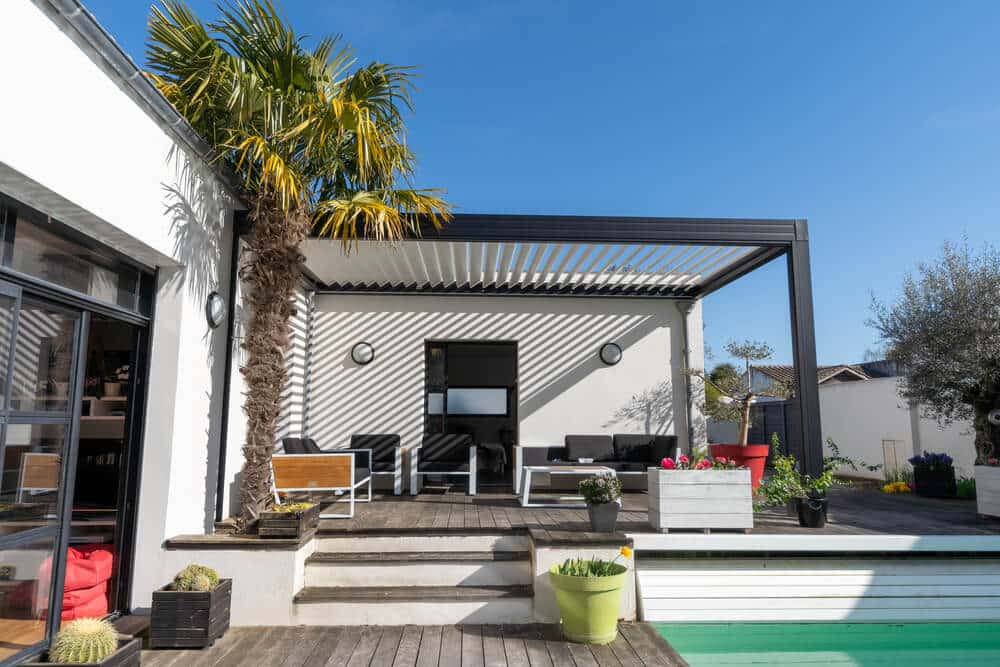
A cover mounted to the house wall below the roof edge could fall into more than one of these cases, so ask the evaluator how your design would be classified before you commit to it. In its requirements for the Silver designation level, the standard also addresses attached structures directly: “Attached structures such as porches and carports must have adequate connections for uplift pressures based on site design wind speed and exposure category.” Our guide to attached vs. freestanding patio covers covers the design tradeoffs, and our patio covers page shows the insulated and aluminum options we build. Planning to close it in later? See our guide to enclosing a patio in the New Orleans metro.
Insurance questions to settle before you build
Louisiana Revised Statutes 22:1483 requires insurers that submit rates and rating plans to the commissioner to “provide an actuarially justified discount, credit, rate differential, adjustment in deductible, or any other adjustment to reduce the insurance premium” for structures built or retrofitted to the State Uniform Construction Code or IBHS FORTIFIED standards. The statute says the credit or discount applies only to policies that provide wind coverage, and its text doesn’t name a percentage, so ask your agent how the discount on your policy is figured today.
Before a cover goes up, ask your agent whether the change affects your FORTIFIED discount and how your policy treats an attached cover compared with a freestanding one. LDI’s consumer guide to homeowners insurance also suggests talking to your producer “to determine the current value of your home using replacement cost estimates or appraisals,” and an addition is a good moment to revisit that. Our hurricane season patio prep guide covers the rest of the storm checklist.
Checklist before adding a patio cover to a FORTIFIED roof home
- Find your FORTIFIED certificate and note its issue date, since designations are valid for 5 years.
- Talk with a FORTIFIED evaluator before design, and share the planned attachment method.
- Ask your installer to show attachment details in the drawings, including any roof penetrations and flashing.
- If your roof was upgraded through the Louisiana Fortify Homes Program, review the program’s homeowner responsibilities with LDI before changing the roof.
- Pull the permit your city or parish requires, as our patio cover permit guide explains.
- Call your insurance agent before the work starts and again when it’s finished.
We build both freestanding and attached covers, and we can put the attachment details in writing for your evaluator to review. When a project also involves the main roof, our roofing team can coordinate the details, and our Kenner patio covers page shows how we engineer covers for open, windy lots.
Frequently asked questions
Will adding a patio cover void my FORTIFIED Roof designation?
No FORTIFIED or LDI source we reviewed says a patio cover automatically voids a designation. The FORTIFIED bulletin says a cover whose roof ties into the main roof cover must meet FORTIFIED Roof requirements, while a completely separate accessory roof isn’t required to for the Roof level. It also says an accessory roof that prevents FORTIFIED edge details on the main roof limits the home to the Existing Roof designation. Talk with a FORTIFIED evaluator about your design before you build.
Is a freestanding patio cover the safer choice for my discount?
We can’t promise how any insurer or evaluator will treat your project. The FORTIFIED bulletin treats an accessory roof as completely separate only when adequate vertical separation keeps materials from touching and the accessory roof won’t interfere with FORTIFIED components on the main roof, such as edge details, so a freestanding cover set close to the roofline may not qualify. FORTIFIED makes the designation call from your evaluator’s documentation, and your insurance company decides how your discount is figured.
Is the Louisiana Fortify Homes Program open right now?
As of September 15, 2026, the Louisiana Department of Insurance’s program page says lottery registration is closed and additional grant rounds will be announced at a later date. Check LDI’s Fortify Homes page for the current status.
Planning a patio cover on a FORTIFIED roof home in the New Orleans metro? We’ll walk the site with you and document how the cover attaches, so your evaluator and insurance agent have the details to review. Call (504) 285-2659 or reach out through our contact page to set up a walkthrough.


